Landlord Insurance in Illinois: Costs, Requirements & Best Providers
Illinois landlord insurance runs above the national average. The homeowners benchmark is $3,240 a year, and landlord policies usually cost 15-25% more. Downstate, tornadoes, hail and derechos drive the price; in Chicago, the claim that catches landlords is a flooded basement. Get a landlord insurance quote and make sure it includes sewer and water backup coverage, which most base policies leave out.
By LandlordTested editorial teamPrices checked
We may earn a commission if you sign up through links on this page. It never changes a ranking. How we make money.
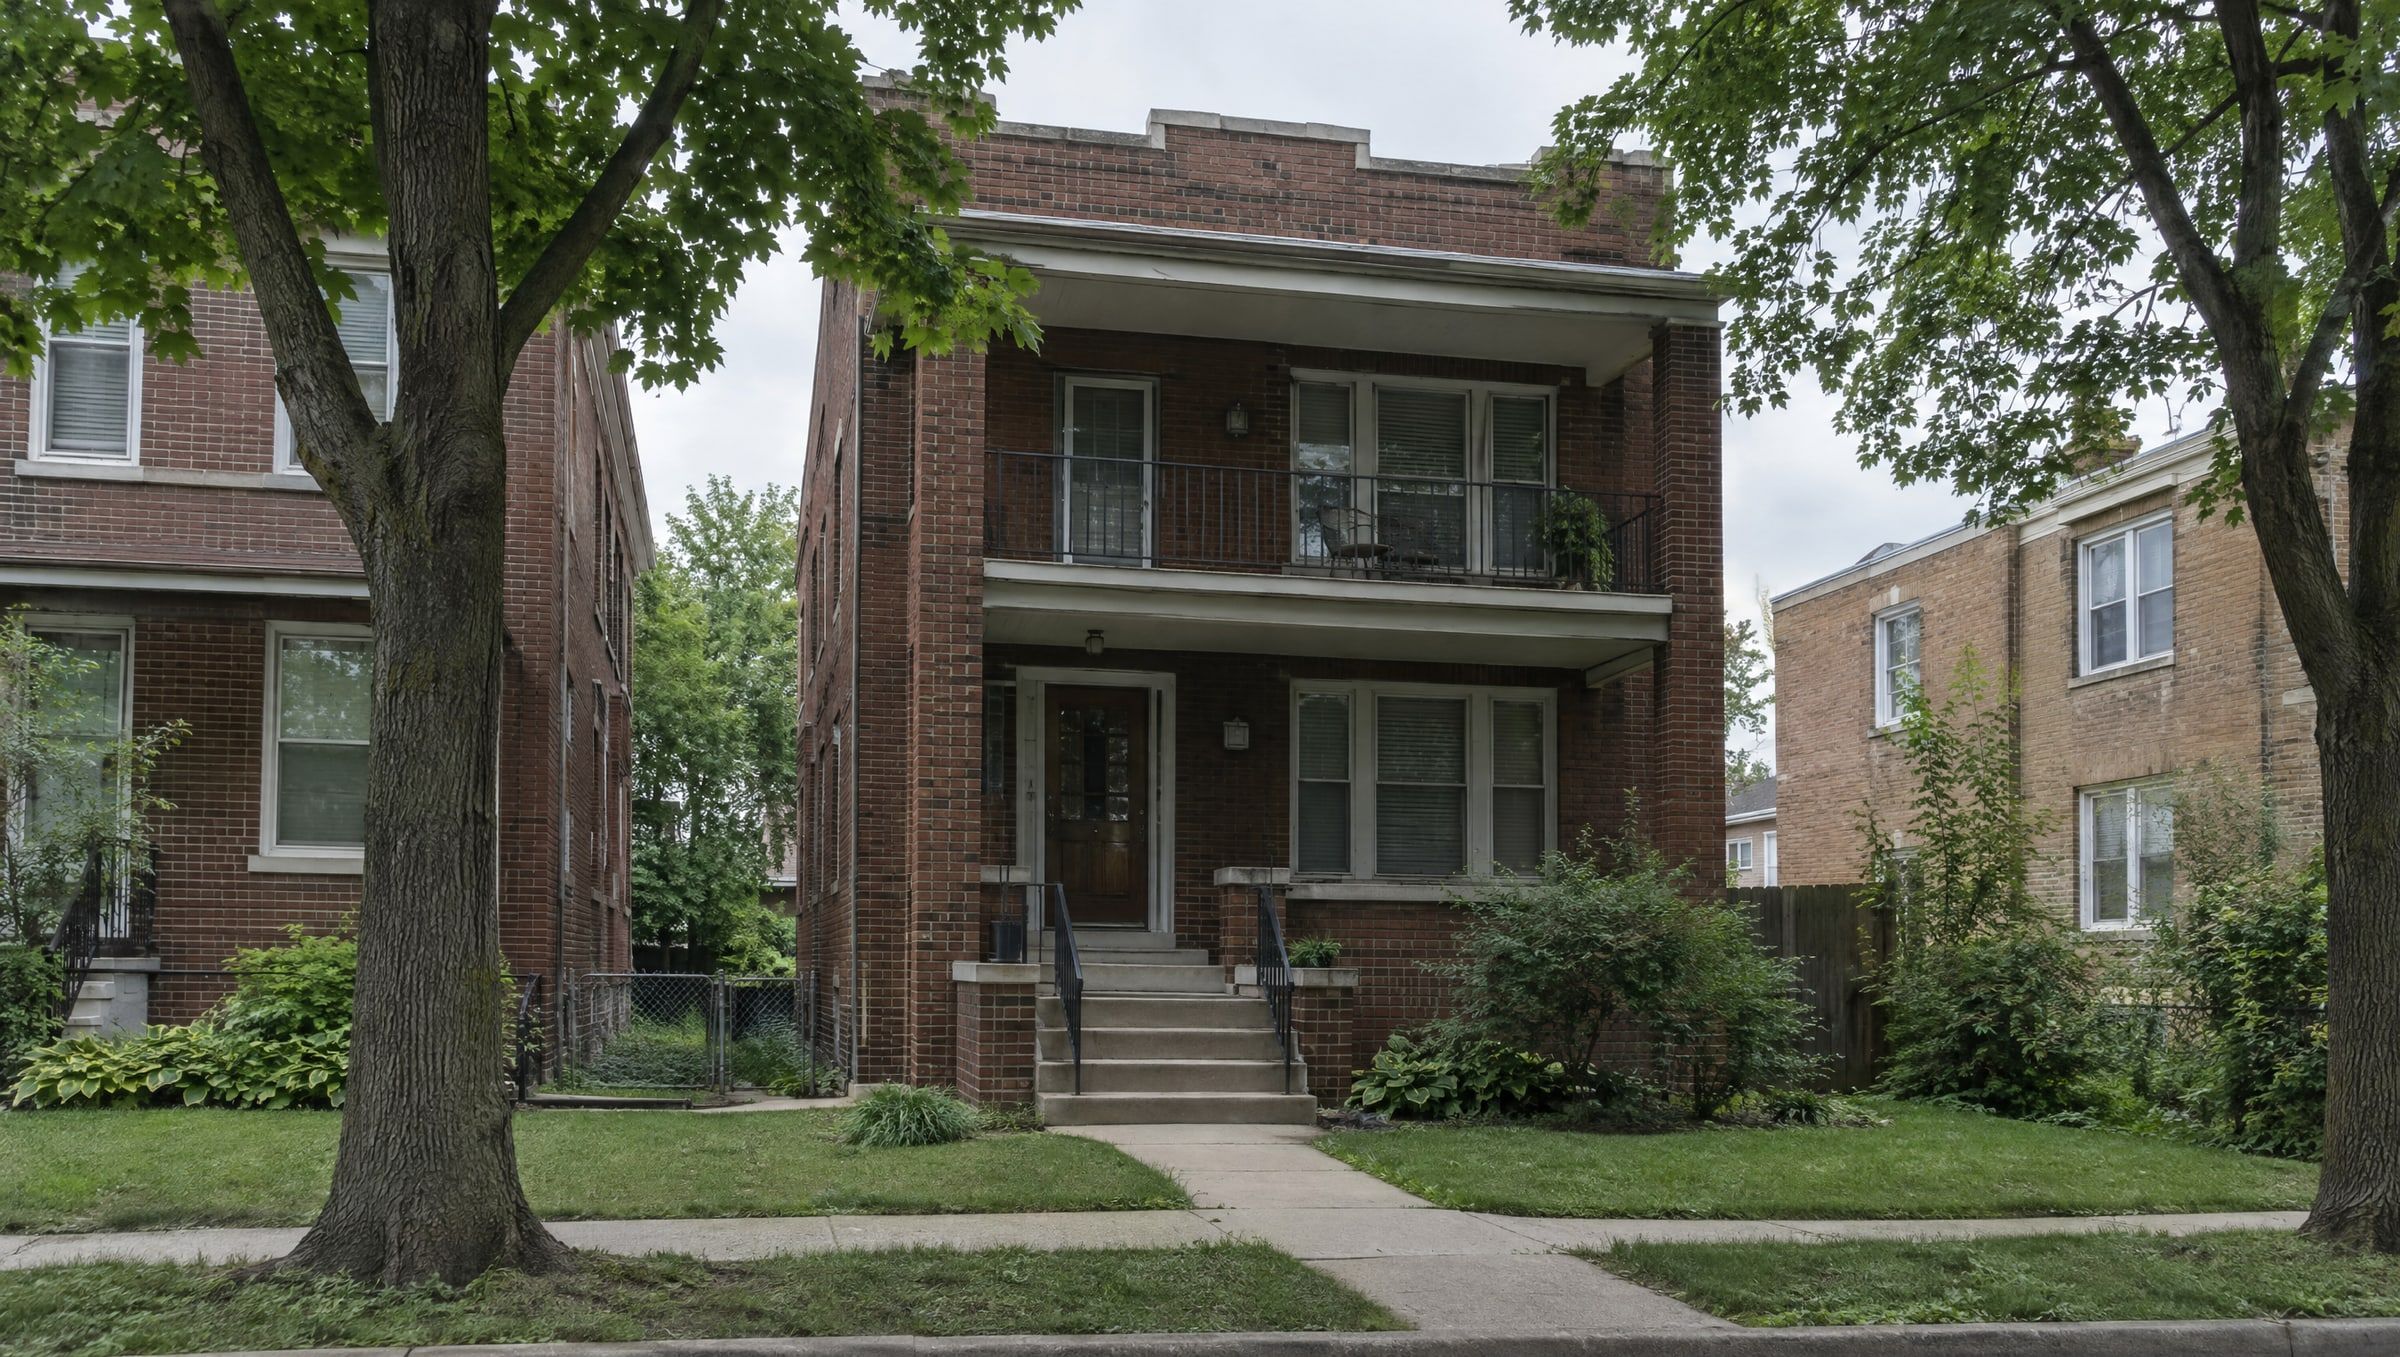
What landlords pay in Illinois
- Homeowners benchmark
- $3,240 a yearAbout $270 a month; 30% above the $2,490 national average.
- Estimated landlord policy
- $3,750-$4,050 a yearLandlord (DP-3) cover typically runs 15-25% above homeowners cover on the same building. Your quote will differ.
- Main hazards
- Tornado, Hail, Wind/derecho, Winter storm/freeze, Flood
- Not included
- Flood and earthquakeBoth need separate policies (NFIP or private flood; earthquake endorsement or policy).
Source: NerdWallet, 2026 homeowners (HO-3) median, $400,000 dwelling cover
Landlord insurance providers in Illinois
Both write landlord policies in all 50 states and quote online. Neither publishes prices, so the only way to know your premium is to get a quote for your address.
- 1
Steadily
Our pickSingle-family and 2-4 unit rentals, including vacant and short-term.
8.5/10 provisionalPrice
Quote-based
Pros, cons and who should skip itHide details
Good
- Covers all 50 states.
- Fast online quotes.
- Writes vacant and renovation properties too.
Watch out
- Mixed claim experiences, including wear-and-tear denials.
- Underwritten through a carrier some lenders have queried.
- Flood needs a separate policy.
Skip it if
Anyone who wants a local agent sitting across the desk.
- 2
Obie
Investors with several properties; portfolio policies available.
8.1/10 provisionalPrice
Quote-based
Pros, cons and who should skip itHide details
Good
- All 50 states plus DC.
- Portfolio (blanket) policies for several rentals.
- Covers short-term rentals and renovations.
Watch out
- Claims run through third-party administrators.
- Some reports of non-renewal after claims.
- Support is mostly email.
Skip it if
Landlords who want claims handled by the company they bought from.
Prices checked Oct 18, 2026. Scores are provisional until our account tests are done.
Want to see how Illinois compares? We keep a table of landlord insurance rates by state, with the method behind every figure.
On this page
What drives Illinois rental premiums
Illinois’s benchmark of $3,240 is about 30% above the national figure. A landlord (DP-3) policy on the same $400,000 house would typically start around $3,730 to $4,050. The state splits into two risk profiles: Chicago and its suburbs, where water is the main claim, and everywhere south, where wind and hail are.
Chicago: water from below
Chicago’s combined sewer system can overflow during heavy rain and push water up through basement floor drains. For landlords with two-flats, three-flats or garden units, that’s a common and expensive claim.
Three kinds of water, three different answers:
| Source | Covered by |
|---|---|
| Burst or leaking pipe inside | Base landlord policy, usually |
| Backup through a drain or sewer line | Sewer and water backup endorsement |
| Surface water from outside | Separate flood policy |
Backup endorsements come with limits, often $5,000 to $25,000. If you rent a finished garden unit, pick a limit that would cover drywall, flooring and lost rent. A backwater valve on the main sewer line reduces the risk and some insurers credit it.
Downstate: tornadoes, hail and derechos
Central and southern Illinois see frequent tornadoes and hail, and the August 2020 derecho flattened trees and roofs from Iowa into northern Illinois. Many policies here use a separate wind and hail deductible, sometimes a percentage of the dwelling limit. A 1% deductible on a $200,000 limit is $2,000 per storm.
Mine subsidence and earthquake
Much of central and southern Illinois sits over old coal mines. In many of those counties, property policies include mine subsidence coverage backed by the Illinois Mine Subsidence Insurance Fund. Confirm it’s on your policy if your rental is in coal country.
Southern Illinois and the Metro East near St. Louis are close to the New Madrid Seismic Zone. Earthquake is excluded from standard policies; an endorsement is worth pricing south of I-70.
Hard-to-insure buildings
Older brick buildings with outdated wiring, vacant units or prior claims can struggle to find coverage. The Illinois FAIR Plan Association is the backstop when the private market declines, with narrower coverage.
What lenders require
Lenders want dwelling coverage at least equal to the loan or rebuild cost, the lender named as mortgagee, and flood insurance in a FEMA special flood hazard area. They don’t usually require sewer backup coverage, which is why so many owners don’t have it.
Ways to pay less
- Install a backwater valve and a battery-backed sump pump, and tell the insurer.
- Replace an old roof before shopping downstate; roof age drives wind and hail pricing.
- Upgrade old electrical panels and knob-and-tube wiring in older Chicago buildings.
- Raise your all-other-perils deductible if you hold the reserve.
- Insure several buildings together through a portfolio policy like Obie’s.
Illinois deposit rules and your risk
Illinois sets no statewide deposit cap, though the Cook County ordinance caps deposits at 1.5 months in suburban Cook County. You must send an itemized statement of damages with receipts or estimates within 30 days after the tenant leaves; without one, the full deposit is due within 45 days (765 ILCS 710/1). Since January 1, 2024, that rule applies to every residential landlord, regardless of building size, and bad-faith withholding can cost twice the deposit plus fees. Chicago and Cook County ordinances also require interest on deposits. A flooded garden unit can look like tenant damage on a move-out checklist, so document backup events when they happen.
Questions landlords ask
The questions we get most, each answered in a paragraph.
How much is landlord insurance in Illinois?
NerdWallet's 2026 benchmark for an Illinois homeowners policy on a $400,000 house is $3,240 a year, about 30% above the $2,490 national average. Landlord policies usually cost 15-25% more. A Chicago two-flat, a Peoria single-family and a Carbondale duplex can price very differently. A quote for the address is the only real number.
Does landlord insurance cover a flooded basement in Chicago?
It depends on how the water got in. Water backing up through a floor drain or sewer line needs a sewer and water backup endorsement, which most base policies exclude. Surface water flowing in from outside is flood, which needs a separate flood policy. A burst pipe is usually covered by the base policy.
What is mine subsidence coverage in Illinois?
It covers damage when the ground settles over old underground coal mines. Standard policies exclude earth movement, but in many central and southern Illinois counties, property policies include mine subsidence coverage backed by the Illinois Mine Subsidence Insurance Fund. Elsewhere it may be optional. Ask your insurer whether your county is covered.