Landlord Insurance in Rhode Island: Costs, Requirements & Best Providers
Landlord insurance in Rhode Island costs a little less than the national average. The homeowners benchmark is $2,230 a year, and a landlord (DP-3) policy typically runs about $2,550 to $2,800. Almost every part of the state is near the coast or Narragansett Bay, so hurricane deductibles are common well inland. Get a landlord insurance quote and check the hurricane deductible before you compare prices.
By LandlordTested editorial teamPrices checked
We may earn a commission if you sign up through links on this page. It never changes a ranking. How we make money.
What landlords pay in Rhode Island
- Homeowners benchmark
- $2,230 a yearAbout $186 a month; 10% below the $2,490 national average.
- Estimated landlord policy
- $2,550-$2,800 a yearLandlord (DP-3) cover typically runs 15-25% above homeowners cover on the same building. Your quote will differ.
- Main hazards
- Hurricane, Nor'easter, Coastal flood, Winter storm, Wind
- Not included
- Flood and earthquakeBoth need separate policies (NFIP or private flood; earthquake endorsement or policy).
Source: NerdWallet, 2026 homeowners (HO-3) median, $400,000 dwelling cover
Landlord insurance providers in Rhode Island
Both write landlord policies in all 50 states and quote online. Neither publishes prices, so the only way to know your premium is to get a quote for your address.
- 1
Steadily
Our pickSingle-family and 2-4 unit rentals, including vacant and short-term.
8.5/10 provisionalPrice
Quote-based
Pros, cons and who should skip itHide details
Good
- Covers all 50 states.
- Fast online quotes.
- Writes vacant and renovation properties too.
Watch out
- Mixed claim experiences, including wear-and-tear denials.
- Underwritten through a carrier some lenders have queried.
- Flood needs a separate policy.
Skip it if
Anyone who wants a local agent sitting across the desk.
- 2
Obie
Investors with several properties; portfolio policies available.
8.1/10 provisionalPrice
Quote-based
Pros, cons and who should skip itHide details
Good
- All 50 states plus DC.
- Portfolio (blanket) policies for several rentals.
- Covers short-term rentals and renovations.
Watch out
- Claims run through third-party administrators.
- Some reports of non-renewal after claims.
- Support is mostly email.
Skip it if
Landlords who want claims handled by the company they bought from.
Prices checked Oct 18, 2026. Scores are provisional until our account tests are done.
Want to see how Rhode Island compares? We keep a table of landlord insurance rates by state, with the method behind every figure.
On this page
Hurricane deductibles reach most of the state
Rhode Island is small, and Narragansett Bay pushes salt water deep into it. Providence, Warwick, East Providence, Bristol and Newport all sit on the bay, so insurers treat a wide band of the state as coastal. The 1938 hurricane and Hurricane Carol in 1954 both drove storm surge into downtown Providence, which is why the city later built the Fox Point Hurricane Barrier.
Most Rhode Island policies carry a separate hurricane deductible, set as a percentage of the dwelling limit. Some carriers also limit new business near the water. If private insurers decline you, the state’s FAIR Plan (the Rhode Island Joint Reinsurance Association) offers basic property coverage as a last resort.
Triple-deckers and older multifamily
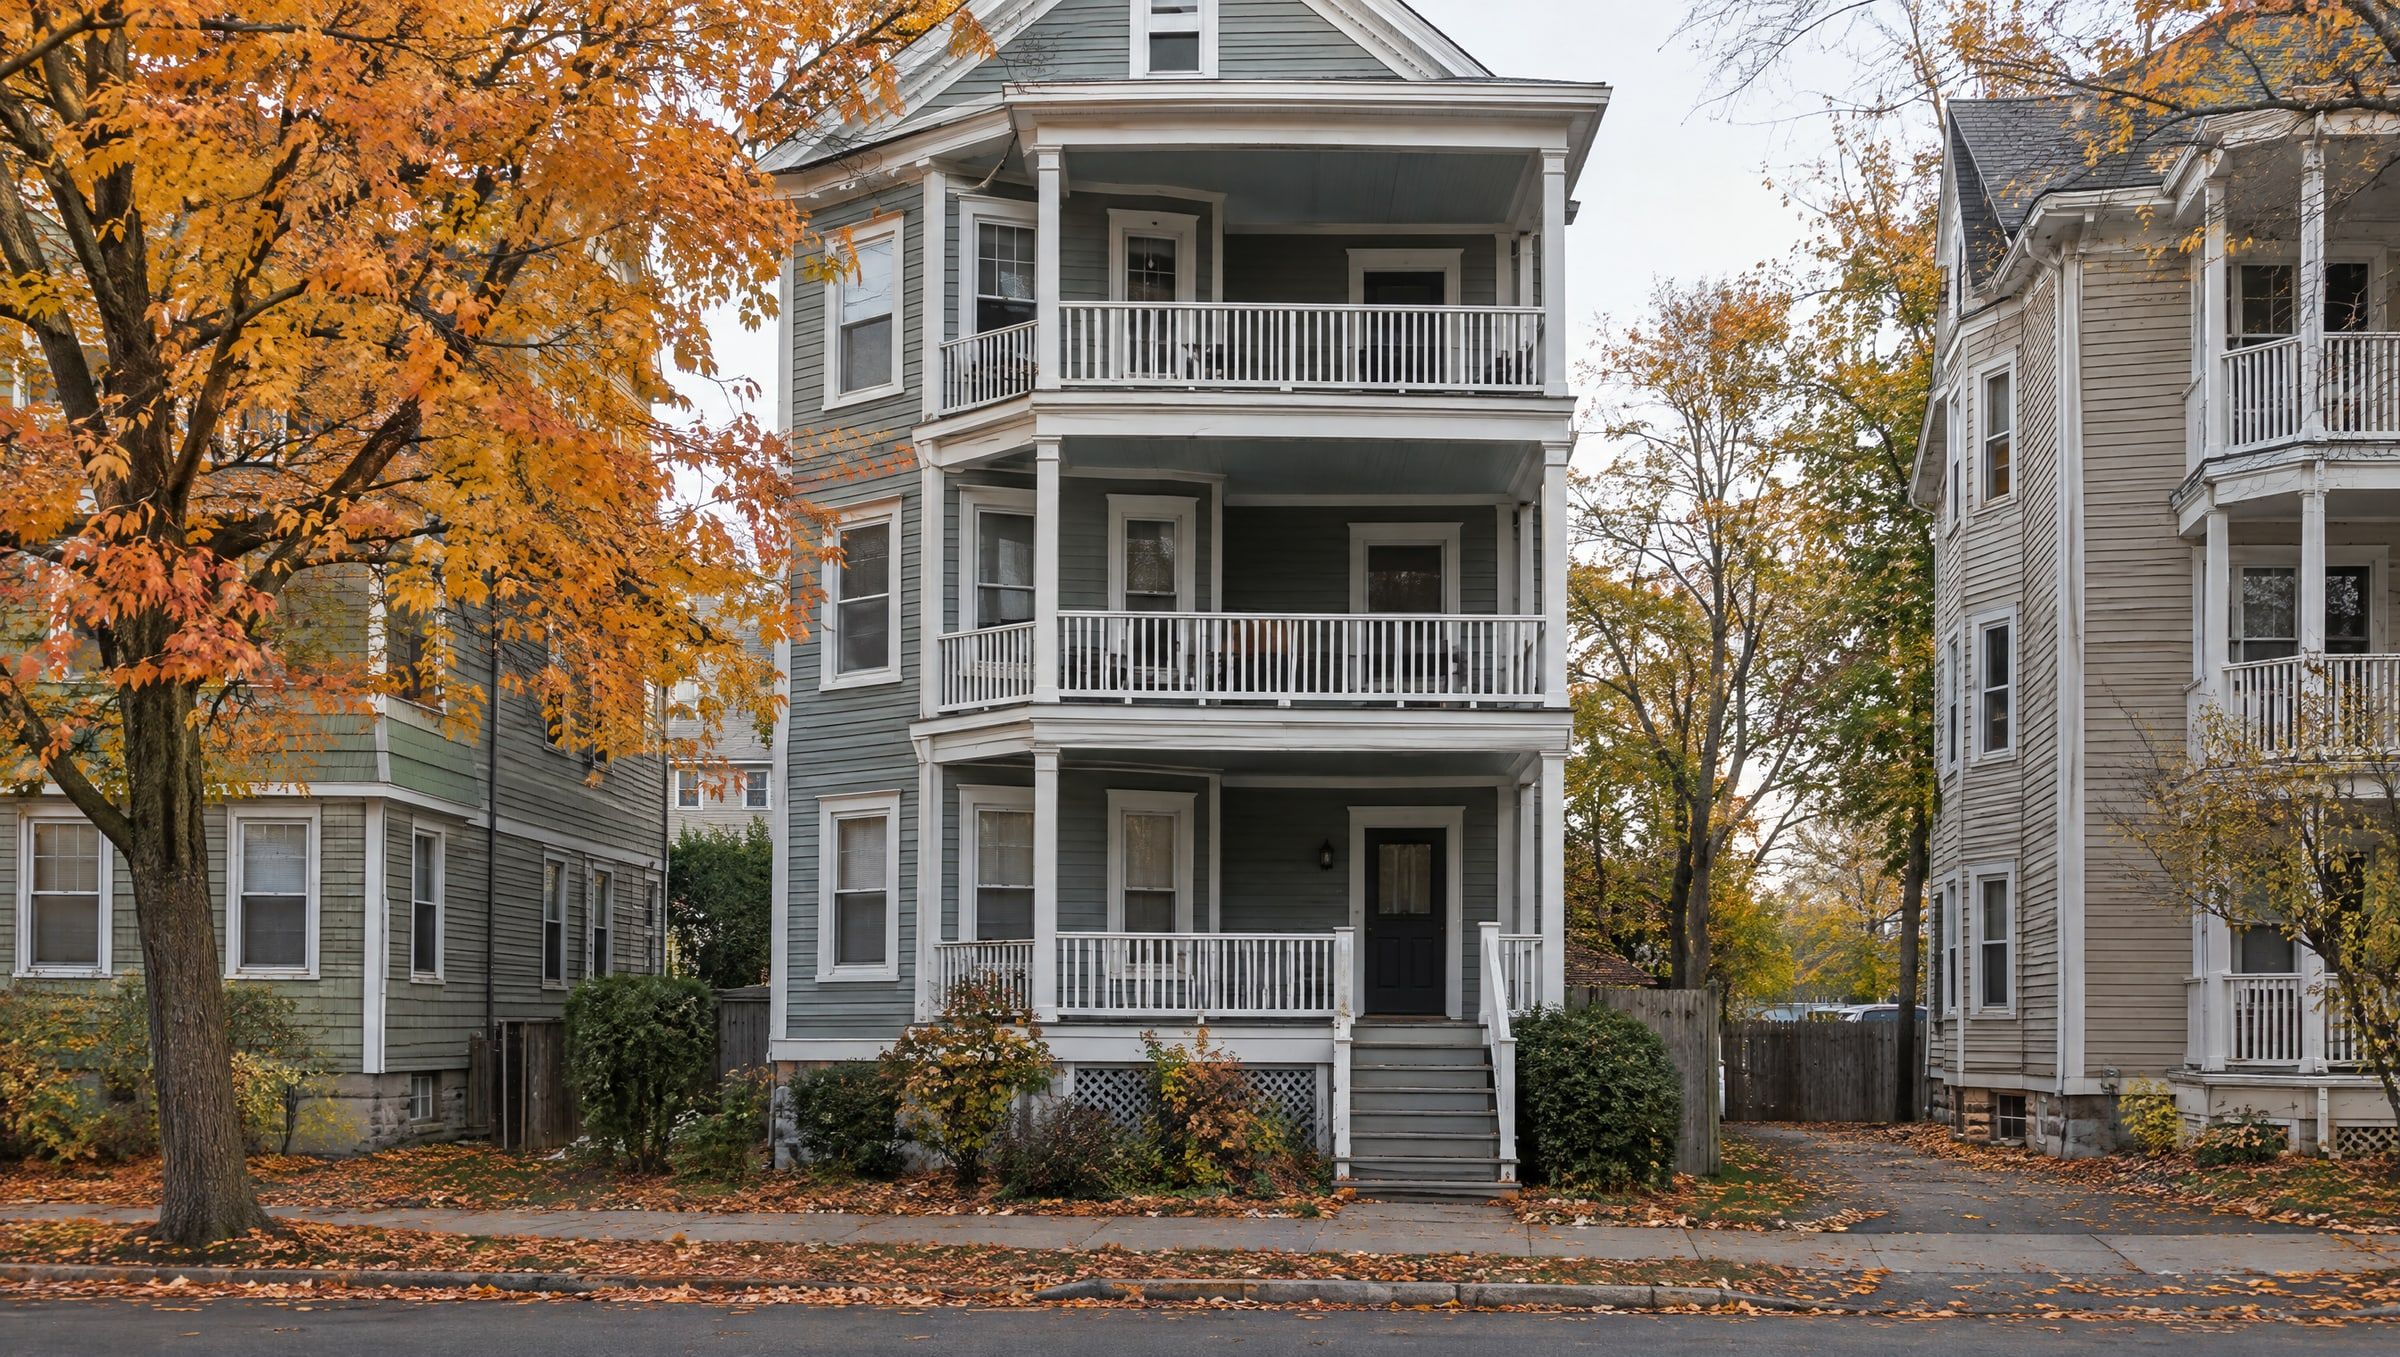
A large share of Rhode Island rentals are two- and three-family homes built in the early 1900s in Providence, Pawtucket, Central Falls, Woonsocket and Cranston. Underwriters look at:
- Wiring and panels, especially knob-and-tube or fuses.
- Heating systems and oil tanks.
- Porches and stairs, which drive liability claims on multi-story buildings.
Updating a panel or rebuilding rear stairs can open up more carriers and lower your liability risk.
Flood is separate
Storm surge in coastal towns and river flooding along the Pawtuxet (which flooded badly in 2010) are both excluded from landlord policies. Coverage comes through the National Flood Insurance Program or a private flood insurer, usually after a 30-day wait. Sewer backup into a basement needs its own endorsement.
What lenders require
Lenders require a landlord policy naming them as mortgagee, with dwelling coverage at least equal to the loan or rebuild cost. Flood insurance is mandatory on federally backed loans in a mapped high-risk zone. Investor lenders commonly require loss-of-rent coverage, and some won’t accept a very high hurricane deductible.
Ways to bring the premium down
- Install hurricane-rated windows or shutters on coastal rentals and ask for mitigation credits.
- Replace an old electrical panel before you shop.
- Get an elevation certificate for properties in flood zones so the flood quote reflects the building.
- Raise your all-perils deductible while keeping the hurricane deductible manageable.
- Require renters insurance with liability coverage from every tenant.
Rhode Island deposit rules
Rhode Island caps deposits at one month’s rent, with an extra furniture deposit allowed when furnishings are worth $5,000 or more (R.I. Gen. Laws § 34-18-19). You must return it within 20 days after the tenancy ends, the tenant moves out and you receive a forwarding address, with an itemized list. Wrongful retention costs double. A rent demand notice can’t be served until rent is 15 days late, which lengthens the gap before you can act on nonpayment.
Questions landlords ask
The questions we get most, each answered in a paragraph.
How much is landlord insurance in Rhode Island?
Rhode Island's homeowners benchmark is $2,230 a year for $400,000 of dwelling coverage (NerdWallet 2026). Landlord policies typically cost 15% to 25% more, or about $2,550 to $2,800. A triple-decker in Pawtucket and a rental in Narragansett or Westerly can be far apart once wind and flood are priced, so quote the real address.
What is a hurricane deductible in Rhode Island?
It's a separate deductible for damage from a hurricane, usually a percentage of the dwelling limit. A 2% hurricane deductible on a $400,000 dwelling limit means you pay the first $8,000. These deductibles are common across Rhode Island because so much of the state is close to salt water. Your regular deductible still applies to other claims.
Can I insure a triple-decker I live in with a homeowners policy?
Often, yes. Many insurers write owner-occupied two- to four-unit buildings on a homeowners policy that accounts for the rented units. Tell the insurer exactly how many units you rent. If you move out and rent every unit, you'll need a landlord (dwelling) policy instead, since a homeowners policy assumes you live there.